A tiny Storypie tale about insurance for families
I tell a tiny Storypie tale about insurance for families when the evening is calm. Once, a riverside village kept a bright jar at the town hall. Everyone dropped a coin when they could. The jar helped when storms knocked roofs loose. It paid for medicine when the baker fell ill. People called it a tiny, wonderful jar of courage. They learned to plan together and to be brave, not afraid.
Read or listen to a story about Insurance now: For 3-5 year olds, For 3-5 year olds, For 6-8 year olds, For 8-10 year olds, and For 10-12 year olds.
How insurance for families works
Insurance for families helps people share and manage risk. Many people pay small amounts called premiums. Those premiums go into a common pool. If bad things happen, the pool helps pay costs. Usually you pay an excess or deductible first. Policies state what they cover and what they exclude. A beneficiary is who receives money from a life policy. For example, a family may claim help after a flood, or to cover medical bills. In fact, in 2024, about 92.0 percent of Americans had health insurance for some or all of the year, showing how essential this safety net is for families.
Types families meet often
Families often find these common forms of cover. Each one protects a different need.
- Life insurance: replaces income when a breadwinner dies.
- Health insurance: helps pay doctor and hospital bills.
- Home insurance: covers buildings and contents after loss.
- Car insurance: pays for repairs and medical costs after accidents.
- Travel insurance: covers medical bills abroad and lost luggage.
- Pet insurance: helps with vet bills for beloved pets.
- Income protection: supports families if someone cannot work.
A short history note
Insurance ideas go back many centuries. Ancient merchants and medieval guilds pooled risk. Later, Lloyds coffee house grew into Lloyds of London. The Great Fire of London made people think about fire cover. Actuarial work began with life tables, like Edmond Halley’s. Over time, social insurance and government safety nets developed. Today, the global insurance industry is thriving, with premiums increasing by an estimated 7.5 percent in 2024, marking the fastest growth since 2006.
Why insurance for families matters
Insurance reduces worry and helps families rebuild. I remember my neighbor after a small flood. She said having a plan eased her breath. However, insurance is not a full guarantee. Limits and exclusions still exist. Therefore prevention matters. Smoke alarms, seatbelts, and saving for small costs remain vital. Also, knowing your policy rules helps avoid surprises. It’s also important to note that in 2025, about 28.0 million people in the U.S. were uninsured, highlighting the ongoing need for families to consider their coverage options carefully.
Three simple parent tips
- Use metaphors kids understand, like a shared jar or umbrella.
- Teach two words, premium and claim, and make a tiny game.
- Reinforce prevention alongside cover as a brave little habit.
Quick consumer checklist
- Check what is covered and what is excluded.
- Know your excess or deductible and plan for it.
- Check replacement cost versus market value for items.
- Keep receipts, photos, and records for claims.
- Review beneficiaries and cover after life changes yearly.
- Shop around and be honest on applications.
- Know how to contact your insurer and where to complain, for example to local ombuds services.
Tonight try this gentle activity
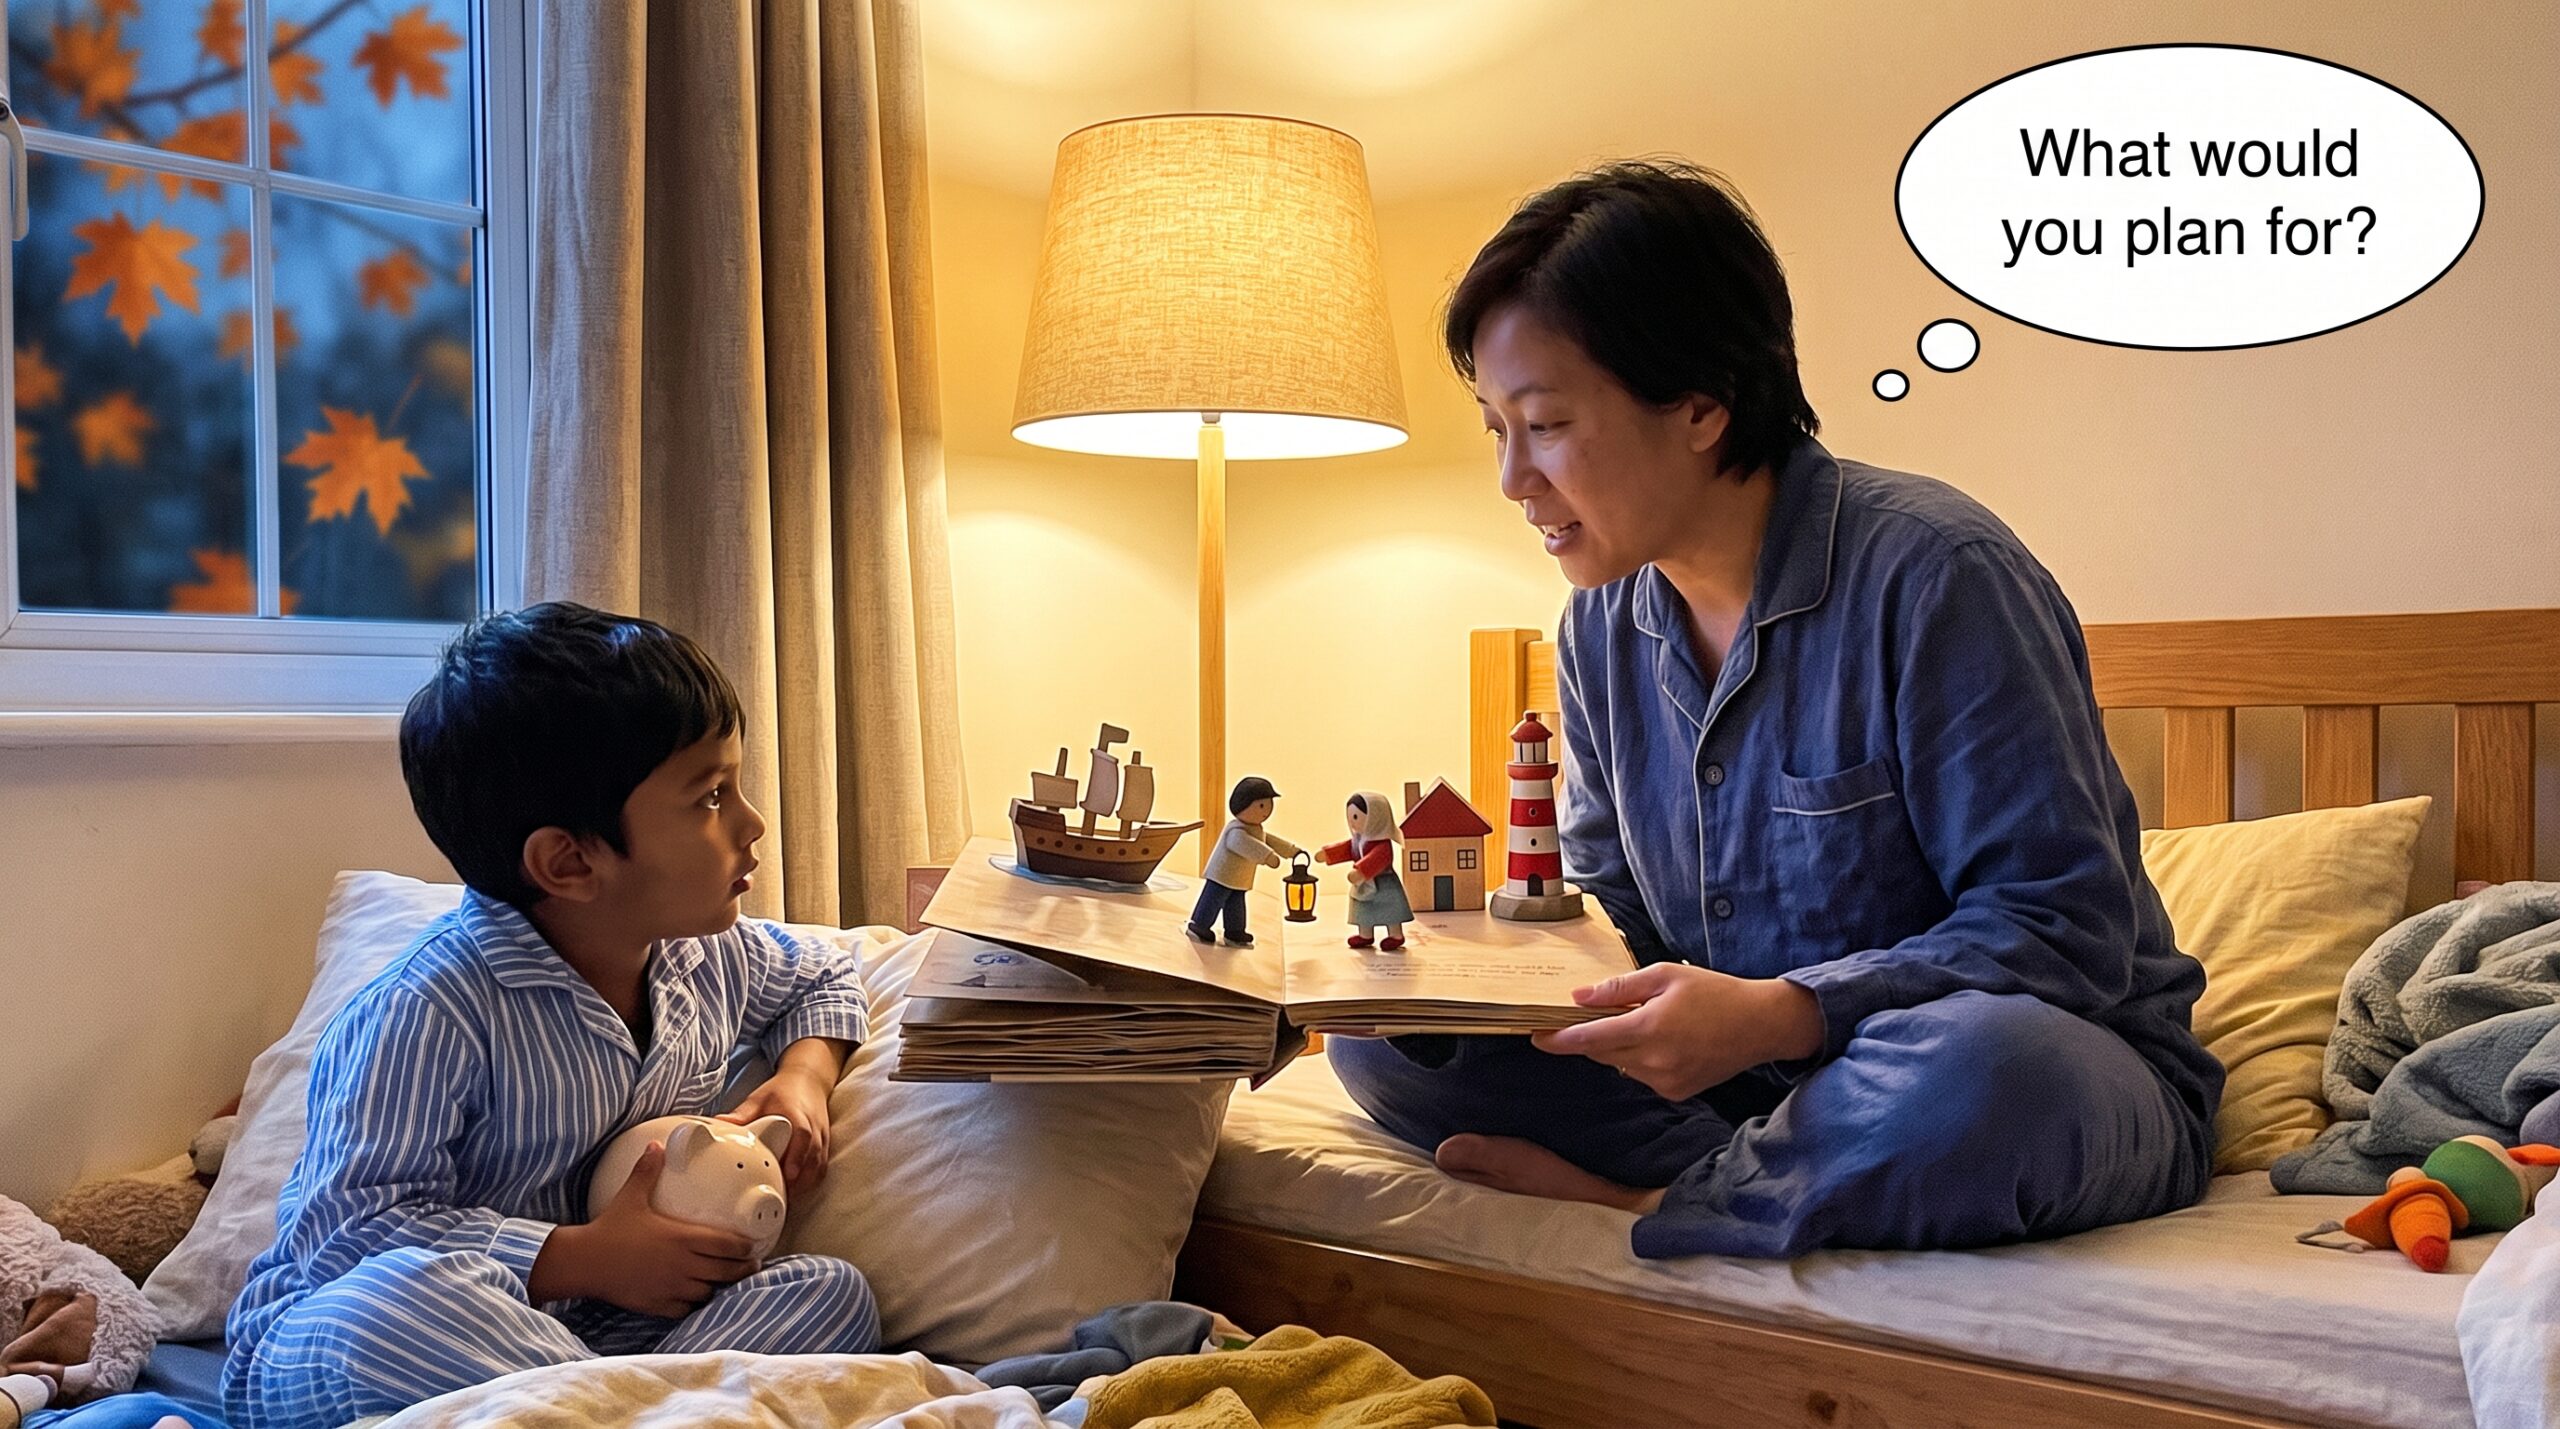
Ask your child, What would you plan for? Then draw your plan together. Small planning is a kind, brave way to turn worry into action.
For more stories and child-friendly explanations, visit Storypie and our insurance collection.